Adapt or die.
It’s an ages old edict, but one that is even more applicable today than in times past.
This is due to the outsized impact robotics is starting to have on multi-trillion dollar industries and Miso Robotics is at the forefront of one. But is it a good investment?
Putting the Fast in Fast-Food
The modern fast-food industry was built on a pair of promises.
Low prices and fast service, hence the name, fast-food.
We regularly review private company offerings like this one here on Greenbull. Most recently we asked if Doroni Is A Good Investment and also did a deep dive on blockchain infrastructure company SMX.
Early industry pioneers like Harry Ramsden’s famous fish and chips in the UK and White Castle, built on a low-cost hamburger model in the U.S., thrived. Becoming multi-million dollar businesses and household names.
Today, the global fast-food industry is a trillion-dollar business, but the promises it was built on are breaking.
Inflation has pushed up most combo meals prices threefold over the past 20 years, while average annual labor turnover of 144% has put a strain on the quick, friendly service customers have come to rely on.
As a result, industry growth has stalled.
One startup has set out to solve the persistent problems of understaffed kitchens and rising costs by automating the most dangerous, hard-to-staff position in all of fast-food.
What is Miso Robotics?
Founded in 2016 by Caltech engineers Buck Jordan, David Zito, Robert Anderson, and Ryan Sinnet. Miso’s mission is nothing less than revolutionizing the commercial kitchen.
Following several years of building it’s tech and raising an initial round of capital, one of the largest in equity crowdfunding history, the private company was finally ready to roll out it’s flagship product, Flippy.
Per it’s name, Flippy was initially designed to flip burgers. But after working alongside restaurant operators and gathering invaluable feedback, a greater pain point was identified.
This pain point is the dreaded fry station.
It’s been dubbed “the most dangerous job in the restaurant industry,” because 80% of surveyed employees who have worked in the position have sustained some form of burns according to the National Council for Occupational Safety and Health.
Surface burns are no fun for anyone, making the fry cook position the least popular among kitchen staff
Miso developed the Flippy Fry Station robot to solve this pressing problem and make on the job burn scars and worker’s compensation claims a thing of the past.
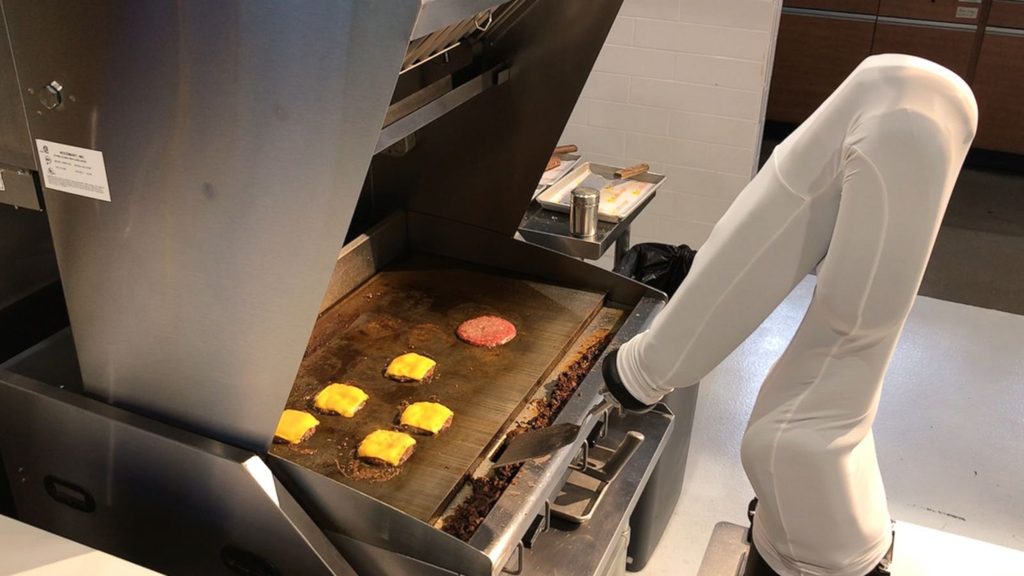
It began piloting the automated robotic arm in March 2017, serving a $4 billion market, that encompasses every eating establishment making fried foods like french fries, onion rings, chicken nuggets, etc.
Honestly, all of this is starting to make me hungry, but what these initial pilots showed was that Flippy was two times faster than human fry cooks, while costing approximately $3 per hour to operate, and importantly, it neutralized oil burns.
Over the past nine years Miso has been building on this initial success, deploying Flippy inside the commercial kitchens of White Castle, Jersey Mike’s Subs, Cinnabon, and other well-known national chains.
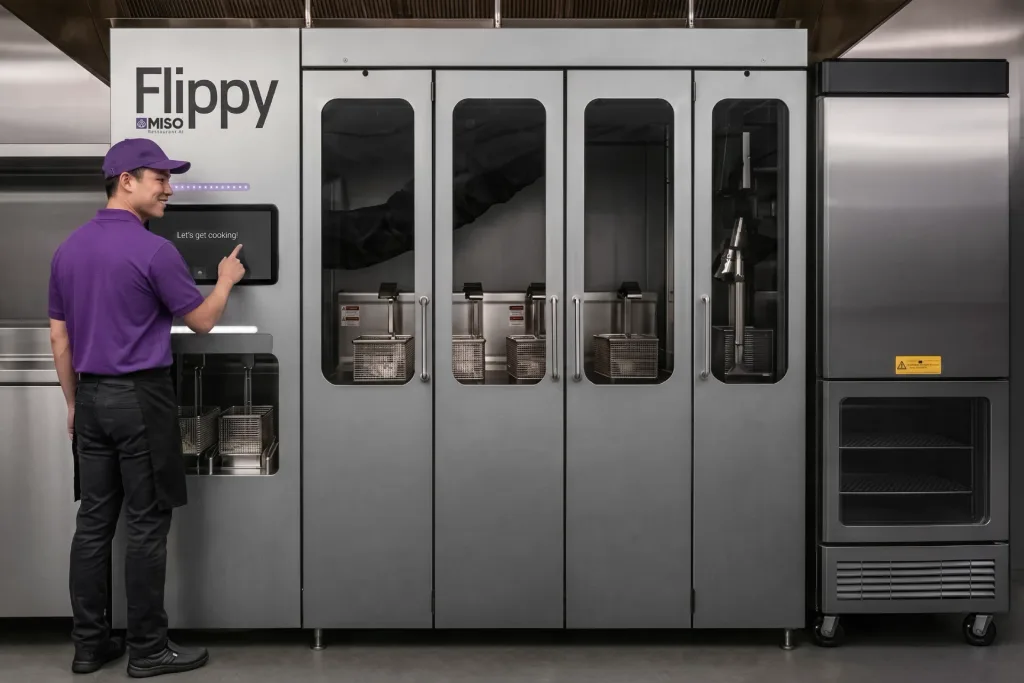
But it hasn’t stopped there.
Miso made two acquisitions this year:
- Zippy, the interface and intelligence layer to Flippy, which provides operators with real-time kitchen data.
- The technology and intellectual property (IP) assets of Zume, suggesting expansion beyond the frying station to pizza preparation.
Now, with a solid technological foundation in place and a growing revenue base, Miso has set its sights on “modernizing the preparation of food and the entire supply chain of the food industry.”
To do this and scale up operations the company is asking private investors for a fresh round of equity capital. Let’s find out if it’s terms are as enticing as the food it prepares.
Is Miso Robotics A Good Investment?
An ambitious target, a deadline, and dilution.
This is how I would sum up Miso’s offering. But before breaking it down, these are the terms:
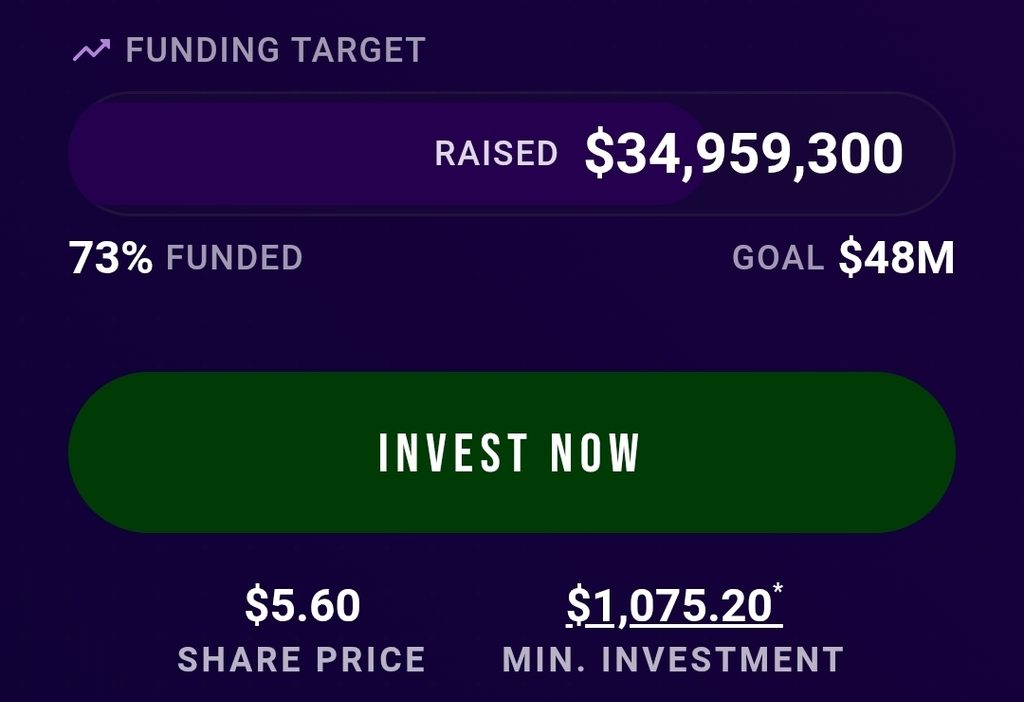
It amounts to 9,124,088 common shares if the target amount is met, including all potential bonus shares issued to participating investors.
Post-offering, assuming full take-up, Miso will have 72,013,732 common shares, preferred stock, warrants, and options outstanding. At today’s offering price of $5.60 per share, that would give the company a valuation of $403.2 million.
Is this good, bad, or somewhere in the middle?
Based on present-day financials, it’s not good.
Miso’s most recent half-year financials from June show the following:
- Net Revenue: $323,630
- Net Loss: $16.2 million
- Cashflow from operating activities: Negative $9.5 million
But perhaps there’s some salvage to be found in the balance sheet?
The company’s recent accounts show cash and equivalents of $7.4 million and $934k in intangible assets against $1.8 million in total liabilities and no debt, after discounting the $7.8 million subscription liability for proceeds received for shares that have not as yet been issued.
Our simple arithmetic leaves us with a book value of $6.5 million.
Paying more than 1,000x sales and 60x book value for any business is not my idea of a good time.
Is the Future Flippy?
Story over substance.
It’s what Miso Robotics’ pitch boils down to, but digging deeper, even the growth story quickly breaks down.
Nearly a decade in, Miso is well past the early research and development stage by it’s own admission. But it’s growth figures are nowhere near explosive enough to justify a unicorn-like multiple.
Total fiscal 2025 revenue was $515k. First half 2026 revenue is $323k, if we extrapolate this out, it will give Miso around $650k in fiscal 2026 revenue.
An implied growth rate of 25%.
Meanwhile, it’s half-year net loss doubled, going from $8.6 million to $16.2 million.
We’re driving in the wrong direction like a blind man on the freeway.
Even if you’re a die-hard believer or longtime bag-holder and see Miso somehow 10x’ing it’s sales in the next year, while operating expenses simultaneously plummet below 2025 levels, a best case scenario if there ever was one. The business is still not worth anywhere near the $400 million valuation it is trying to secure by the end of the year.
A far more realistic base case is double-digit year-over-year growth, slightly smaller losses as less R&D is needed than in earlier years, and continued dilution, with Miso needing additional rounds of funding just to remain a going concern.
Miso Robotics is not a good investment at it’s current pre or post-money valuation.
Quick Recap & Conclusion
- Robotics is expected to be a multi-trillion dollar industry and Miso Robotics is at the forefront of a growing niche. But is it a good investment?
- Miso is the maker of Flippy, an automated robotic arm addressing the major pain point that is the high turnover, high risk of injury fry station in commercial kitchens.
- To continue expanding Flippy distribution and fund other growth initiatives, Miso is seeking to raise $48 million by selling 9,124,088 common shares at a price of $5.60 per share, giving it a fully diluted post-money valuation of $403 million.
- Unfortunately, Miso’s underlying economics do not support it’s ask, with $323k in revenue, a $16.2 million net loss, and 25% sales growth through the first half of the year.
- Miso Robotics cannot justify a 1,000x sales multiple and is not a good investment.
Will the commercial kitchen get completely automated? Tell us what you think in the comments.